Open a typical American household wallet and you will often find four balances, each with a different interest rate, a different minimum payment and a different due date. Each one generates a statement, each one wants a portion of the monthly budget, and each one is quietly accruing interest against a different rate. On its own, none of this is a crisis. Stacked together, it is a structural problem: the household has no single, clear number that represents what it costs to run, and therefore no single, clear number representing what remains.
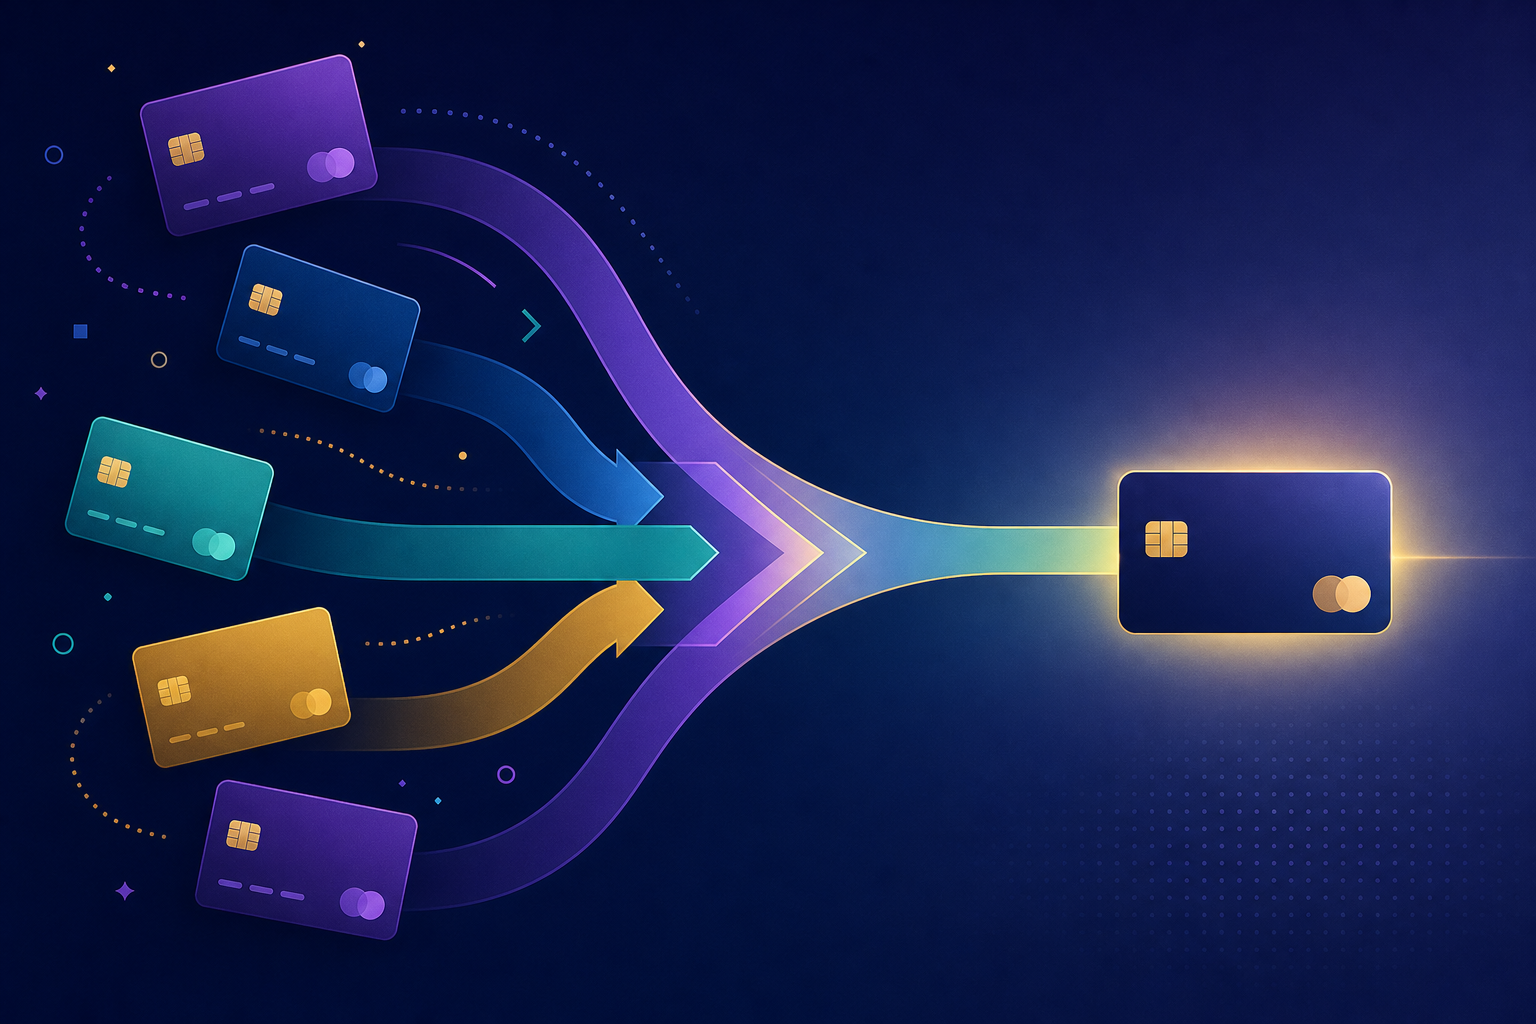
Debt consolidation exists to solve that structural problem. By rolling several balances into one new loan or one lower-rate facility, you reduce the number of payments to manage, lower the total interest in the common case, and create a defined end date. The difficulty is that consolidation is frequently marketed in a way that blurs an important distinction: it is sometimes a genuine improvement, and sometimes simply a repackaging of the same cost with a cleaner presentation.
What consolidation actually does
Consolidation takes multiple separate debts and replaces them with one new obligation. The mechanics are usually one of three things. A balance transfer moves a credit card balance onto a card with a promotional or lower rate, usually with a transfer fee and a promotional window. A consolidation loan pays off several debts with a single new amortising loan at a fixed rate over a set term. A debt settlement programme, which we do not recommend, negotiates with creditors for a reduced balance and is frequently accompanied by credit damage and tax consequences.
The first two are legitimate tools. The third almost never is, and if anyone suggests it, ask what is being cancelled and what the tax treatment will be before you sign anything.
To know whether a consolidation helps, you need one number: the total cost of repayment, in dollars, over the full life of the new arrangement. A new loan with a lower monthly payment and a longer term can look attractive while actually costing more overall, because you are paying the extra balance for longer. Always compare total repayment, not the monthly figure. The monthly payment determines whether you can afford it; the total cost determines whether it was worth it.
When it makes sense
Consolidation is usually a good decision when at least three of the following are true:
- Your highest-cost balance is genuinely expensive. Credit card rates above 20% are the clearest case; consolidating them into a fixed-rate loan below that is a straightforward saving.
- You are paying more than the minimum on multiple accounts. If you are chasing the balances down anyway, a single fixed payment with a defined payoff date is easier to manage and easier to stay on.
- Cash flow is tight enough to cause late payments. One predictable payment removes a whole category of risk, including the credit damage that late payments cause.
- You have been tempted to borrow more. A consolidation loan is a closed-end facility with a fixed balance, which is structurally harder to overspend than a reusable credit card.
- You cannot change the behaviour that created the debt. Sometimes the only realistic route out is to make the payments automatic and remove the temptation to create a new balance.
For most of the clients who come to us with four or five open revolving balances, the combination of a consolidation loan for the expensive balances and a single low-rate card for day-to-day spending resolves the structural problem quickly and durably.
When it does not
Consolidation is the wrong tool in a few identifiable situations, and it is worth being blunt about them. If you are consolidating student loans purely to reduce the monthly payment without changing the total cost, you have usually made the loan more expensive while feeling better about it. If the real problem is spending, consolidation postpones it rather than solving it — the balances may be lower while the underlying pattern continues, and the new limit becomes the next set of balances. And if a lender charges a large origination fee, a 3% origination fee on a two-year loan can consume a meaningful share of the interest you were trying to save.
There is one more case worth flagging: consolidation used to clear a balance and then immediately charging the new balance back onto a card. If you have done this before, be candid with your advisor about it. It changes the recommendation, because the fix then is behavioural rather than financial, and a repayment plan with accountability matters more than a lower rate.
How to do it properly
If you decide to consolidate, the sequence matters. First, pull a full list of every balance, rate and minimum payment, and total the monthly outflow. Second, model at least three options at different rates and terms, and compare the total repayment figure across all of them. Third, check for penalties on the accounts being closed; closing a card with a balance can trigger a fee or trigger the closing of other accounts under the same issuer. Fourth, make sure the new payment is auto-debited from the day it starts, and fifth, write down the target payoff date where you will see it.
Most importantly, decide in advance what the freed-up credit limit is for. The best practice is to ask the new lender for a limit you actually need and to have the old cards formally closed, rather than keeping them open as a temptation. Our advisors will walk you through the closure requests, because a closed card is one of the few genuinely permanent protections available against a repeat of the same spending pattern.
Debt consolidation is not a financial strategy. It is a risk-reduction strategy. Used with discipline it lowers both the cost and the volatility of your obligations; used as a reset button it simply defers the consequences.
If you are unsure which side of that line you are on, that uncertainty is itself useful information, and it is free to explore. Bring your account list to a consultation and we will model the options with you — including the option of doing nothing, which is sometimes genuinely the right answer when your current rates are already low and your balances are already falling.